Repairs vs. Improvements on a Rental Property: Why the Distinction Matters
The IRS treats a repair and an improvement very differently, and the distinction affects your recordkeeping regardless of how you file. Here is how the two are commonly defined, for informational purposes only.
By Home Crane Editors. . 3 min read.
Conceptual illustration of separating rental property expense records.
This article explains a common distinction in rental property recordkeeping, drawn from definitions published in IRS Publication 527, Residential Rental Property. It is provided for general informational purposes only and is not tax advice. Tax treatment depends on your specific situation, and rules can change, so consult a qualified tax professional before making decisions based on this distinction.
Why this distinction exists at all
According to IRS Publication 527, an expense for repairing or maintaining rental property is generally treated differently from an expense that improves it, and the publication states that costs classified as improvements generally must be capitalized rather than deducted immediately. Because the two categories are treated so differently, keeping accurate, separated records of repair costs versus improvement costs as work is done, rather than trying to reconstruct the distinction later, is a practical habit worth adopting regardless of how you ultimately file.
How a repair is commonly described
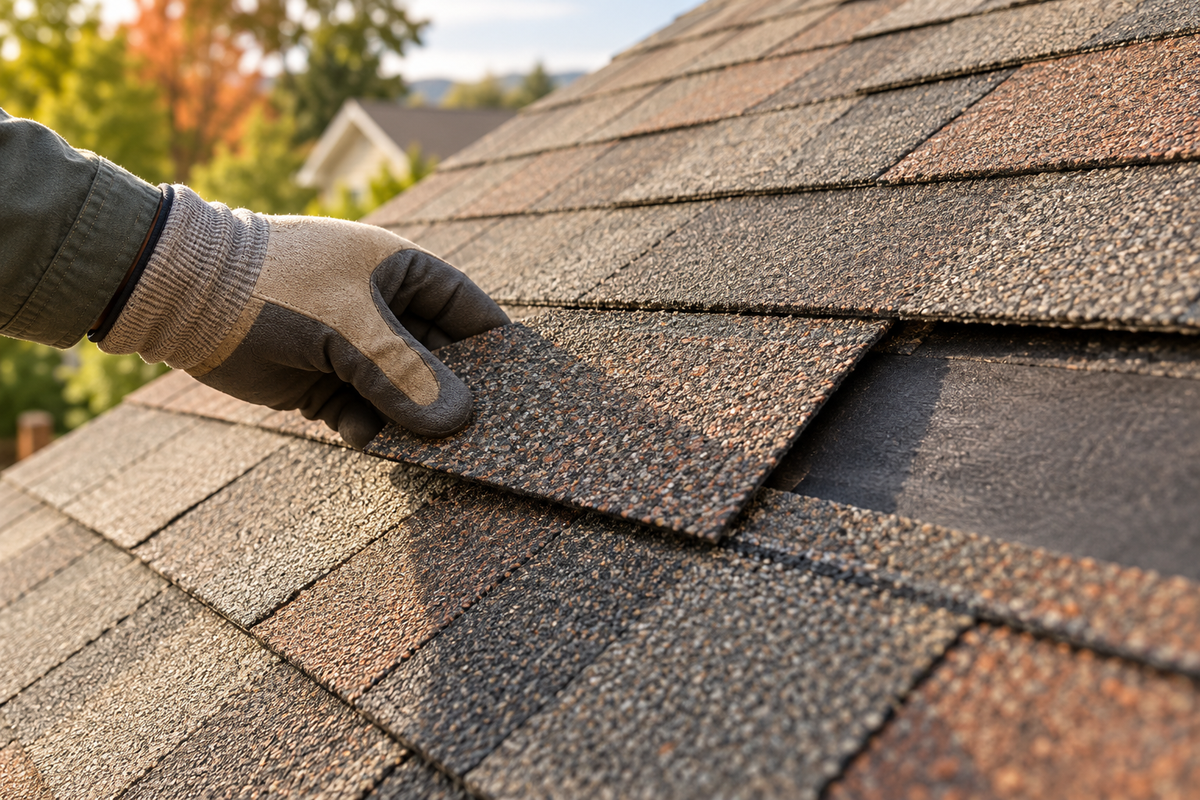
A repair is generally described as work that keeps a property in ordinarily efficient operating condition without adding significant value or extending its useful life substantially. Common examples cited in guidance interpreting Publication 527 include patching a roof, fixing a leak, repainting, or replacing a broken part of an appliance with a similar part.
How an improvement is commonly described
An improvement, by contrast, is described in the publication as an expense that results in a betterment to the property, restores the property, or adapts it to a new or different use. The publication breaks this into three commonly referenced categories:
| Feature | Example description | |
|---|---|---|
| Betterment | Fixing a pre-existing defect, enlarging the property, or increasing its capacity, strength or quality | |
| Restoration | Replacing a substantial structural part, or rebuilding the property to a like-new condition | |
| Adaptation | Altering the property for a use inconsistent with its original intended use |
Guidance interpreting the publication commonly cites examples such as a new roof, an addition, wall-to-wall carpet replacement, or a kitchen update as falling into the improvement category, generally because these add value or extend useful life rather than simply maintaining the existing condition.
An example that trips people up: paint
A frequently cited nuance in guidance interpreting the publication is that even a complete interior and exterior repaint, despite its cost and scope, is commonly treated as a repair rather than an improvement, because it primarily maintains the property's condition rather than adding significant value or extending its life. This example illustrates that cost and scope alone do not determine the category. What matters, per this common interpretation, is whether the work restores, betters or adapts the property versus simply maintaining it.
- Keep receipts and records separated by category as the work happens, rather than sorting them at tax time from memory.
- Note the date, cost and a brief description of what the work addressed for every rental property expense.
- When a project's classification is unclear, such as a major system replacement that could arguably fall into either category, that is a specific reason to consult a tax professional rather than guess.
- Remember that rules and interpretations can change, so treat this article as a starting framework for understanding the concept, not as current, authoritative tax guidance for your specific filing.
Why this distinction is worth tracking even if you use software
Rental property owners increasingly use accounting or property management software that includes expense categories out of the box, and some tools attempt to pre-classify expenses automatically based on the description entered. Automated categorization is a convenience, not a substitute for judgment, particularly for a borderline expense such as a major system replacement or an extensive repair that touches multiple aspects of a property. Reviewing how the software has classified larger or unusual expenses periodically, rather than assuming automation always gets the classification right, is a reasonable habit for any rental property owner.
This ties directly into your operating numbers
Our rental property calculator estimates net operating income based on rent, vacancy and operating expenses, which is a distinct calculation from tax treatment and does not require classifying expenses as repairs or improvements. The calculator's disclaimer applies here as well: it is for general education, not investment, tax or financial advice.
Your takeaway: as you incur expenses on a rental property throughout the year, note whether each one plausibly falls into the repair category or the improvement category as described above, and keep the records separated. When you are unsure, that uncertainty itself is useful information to bring to a tax professional, rather than a decision to make on your own from a general guide like this one.
Frequently asked questions
Is this article tax advice?
No. It explains a common distinction found in IRS Publication 527 for general informational purposes. Tax treatment depends on your specific situation, and you should consult a qualified tax professional before making decisions based on this distinction.
Why is repainting usually treated as a repair even if it's expensive?
Guidance interpreting Publication 527 commonly treats painting as maintaining the property's existing condition rather than adding significant value or extending its useful life, which is the basis for the repair versus improvement distinction, regardless of the cost involved.
Sources
- Schedule E - Repairs and Improvements (summarizing IRS Publication 527), TaxAct support documentation. Checked September 24, 2026
- How are repairs and improvements different? (summarizing IRS Publication 527), WCG CPAs and Advisors. Checked September 24, 2026
Share this article
Get new guides by email
Practical home articles and free resources. No spam, and you can unsubscribe at any time.
Keep reading
11 Ways How To Decorate An Airbnb Bedroom for Cheap
Explore decorate an Airbnb bedroom for cheap with practical US-focused advice, planning checks, and clear steps for a more comfortable, well-maintained home.
November 2026, 8 min read
15 Damage Free Wall Decor Ideas for Renters
Explore damage free wall decor ideas for renters with practical US-focused advice, planning checks, and clear steps for a more comfortable, well-maintained home.
November 2026, 11 min read
13 Clever Rental Friendly Decor Hacks for Apartments
Explore rental friendly decor hacks for apartments with practical US-focused advice, planning checks, and clear steps for a more comfortable, well-maintained home.
November 2026, 13 min read